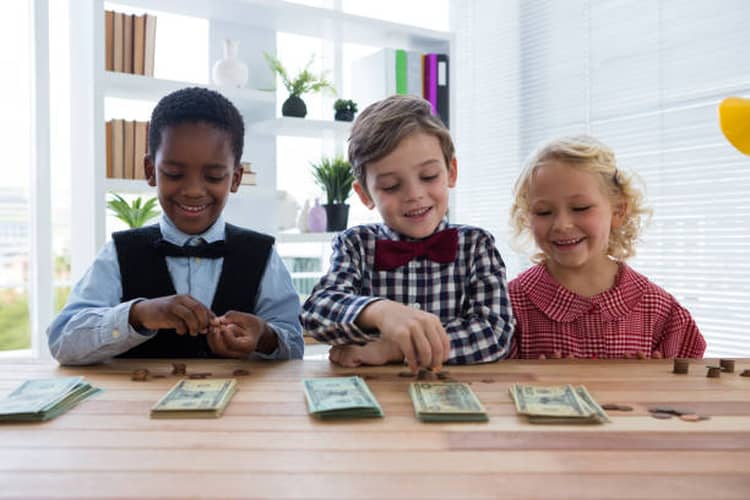
 Did you know that 86% of children ages 7 to 14 have their own money?
Earlier, when I read an article about Gen Alpha kids earning money, I wasn’t surprised. It felt like the article simply put into words something I had already noticed but never really articulated. Gen Alpha children are growing up in a world where they were exposed to the “Buy” button long before they fully understood the concept of money. Information about earning money is available at their fingertips almost instantly.
This is why it’s important for parents to model good financial habits at home. Our kids need to understand that personal finance involves much more than a few clicks and money earned online.
In real life, managing family finances can be exhausting. Unexpected dental bills and car repairs often appear at the worst possible time, especially when rising grocery prices have already stretched the budget. In most households, every paycheck seems to have multiple competing priorities, and the stressful part is that they all feel urgent and important.
Most personal finance blogs portray debt as something that should be avoided at all costs. However, life happens, and sometimes borrowing may be the only practical way to deal with a financial challenge. Borrowing isn’t always a bad thing, but it needs to be approached carefully.
For example, some families use personal loans to consolidate higher-interest debt, cover necessary home repairs, or manage unexpected expenses without relying on multiple credit cards. When used responsibly, a personal loan can provide breathing room and help families address important financial needs.
The key is understanding how debt fits into your overall financial plan and making sure your budget can support it.
Start with a Financial Cushion
While it is easy to think that debt is unavoidable, having a financial cushion can help you deal with unexpected expenses without immediately turning to borrowing. Life is unpredictable, and emergency savings can make a difficult situation much easier to manage.
Having a financial cushion is also an opportunity to show your children what financial discipline looks like in real life. By planning ahead and setting money aside for emergencies, they learn that financial stability is built through consistent habits, not quick fixes.
If you’re trying to build a stronger financial foundation, here are a few priorities worth focusing on:
- Build an Emergency Fund: Aim to save enough to cover three to six months of essential expenses. This can help you handle unexpected costs without relying on credit cards or loans.
- Pay Down High-Interest Debt: Credit card balances often carry some of the highest interest rates. Reducing these balances can free up more money in your monthly budget.
- Make Saving Automatic: Setting up automatic transfers to a savings account can help you stay consistent and build savings over time.
Borrow With a Purpose
Not all debt serves the same purpose. Some borrowing can help support long-term financial goals. Good examples include a mortgage, which allows families to purchase a home without paying the full amount upfront, or a student loan that can lead to better career opportunities. For many families, these loans can make major life goals possible, provided the payments fit comfortably within the household budget.
On the other hand, some borrowing is used for things that provide only temporary satisfaction, even though the payments may stick around for years. Regularly relying on credit cards to pay for shopping, expensive meals, or vacations can become costly, especially when balances are carried from one month to the next.
Before borrowing, ask yourself a simple question: Will this purchase improve my family’s financial position in the long run, or am I creating a payment for something that will be long gone before the debt is repaid?
Understand the Real Cost of Interest
When families are working within a tight budget, it is easy to focus only on the monthly payment. After all, a lower payment may seem more manageable today. However, extending the loan term often means paying significantly more interest over time.
Before signing any loan agreement, take a few minutes to compare different loan terms using an online loan calculator. A payment that looks affordable at first may end up costing thousands more in interest over the life of the loan. Looking at both the monthly payment and the total cost of borrowing can help you make a more informed decision.
Teach Kids About Money
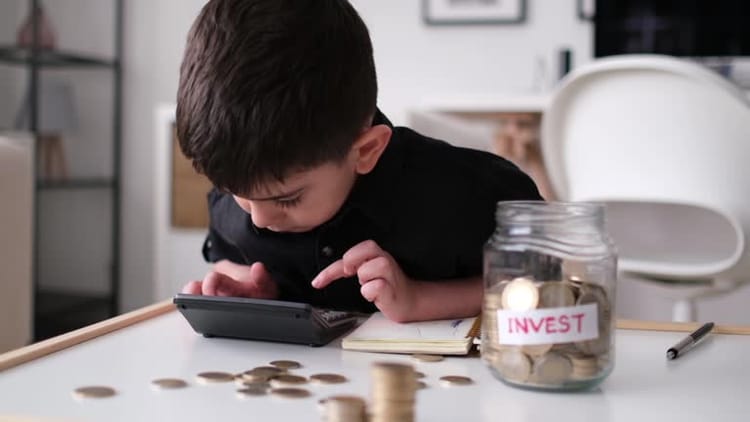 One of the biggest challenges for parents today is that children are exposed to spending money long before they understand how hard it is to earn it. They can watch influencers recommend products, see ads while playing games, and buy things online with just a few taps on a screen.
That is why money conversations should start at home. Parents don’t need to wait until their children are teenagers to talk about budgeting, saving, or making thoughtful spending decisions. In fact, some of the best lessons happen during ordinary family activities.
Here are a few simple ways to get started:
- Let them help with a grocery budget: Give an older child a small amount to spend on ingredients for a family meal. Have them compare prices, add up the cost of items, and decide what fits within the budget. This helps them understand that every financial decision involves trade-offs.
- Try the “Give, Save, Spend” approach: If your child receives an allowance or birthday money, consider dividing it among spending, saving, and giving. Using separate jars or envelopes can help younger children see where their money is going.
- Talk about wants versus needs: When your child asks for something that is not in the family budget, use it as an opportunity to explain how financial decisions are made. Instead of simply saying “no,” talk about saving for it, waiting for a special occasion, or deciding whether it is really worth the cost.
These conversations don’t need to be formal. Some of the most valuable lessons happen in the car, at the grocery store, or while discussing everyday spending decisions. Over time, children begin to understand that budgeting is not about never spending money. It is about making choices, setting priorities, and planning ahead.
Use a Budget to Support Your Goals
A budget is more than just a list of expenses. Having a budget will help your family understand where your money is going and whether your current spending habits support your long-term goals.
For parents, budgeting is also a way to ensure that essential expenses, savings, and debt payments are covered before spending money on non-essential purchases. It provides a clearer picture of how much room is actually available in the household budget for additional expenses or new loan payments.
Before taking on new debt, it is important to see how the payment will fit into your monthly finances. If a new car loan, personal loan, or mortgage payment means reducing retirement contributions, slowing down emergency savings, or constantly worrying about grocery expenses, it may be a sign that the debt is more than the household can comfortably handle.
Final Thoughts
At the end of the day, managing family finances is not about avoiding debt at all costs. It is about understanding when borrowing makes sense, preparing for unexpected expenses, and making thoughtful financial decisions that support your family’s goals.
More importantly, it is about showing our children that money is not just something that appears with a click of a button. By letting them see how we budget, save, borrow, and plan ahead, they learn that financial stability comes from consistent decisions made over time. Those lessons may be just as valuable as anything we can teach them about earning money.
Leave a Reply